





Op_Ed
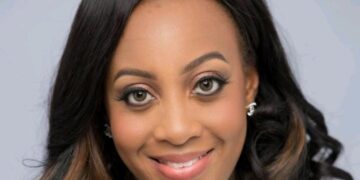
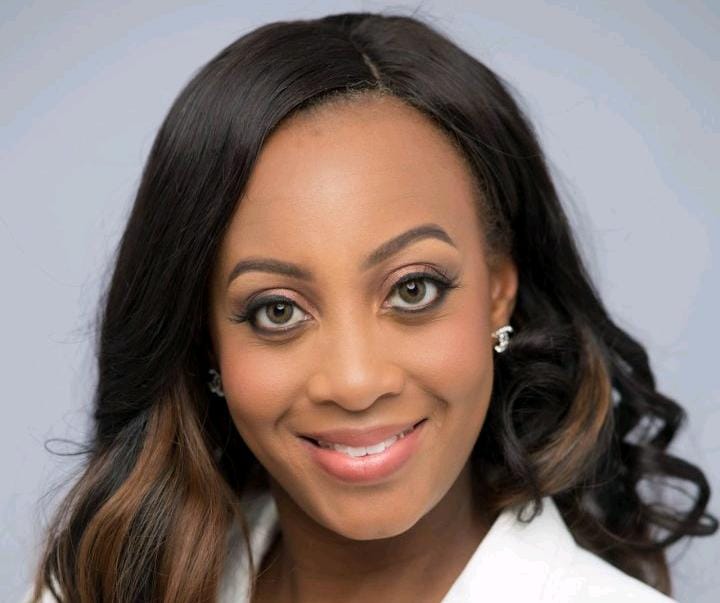
Kimberly Castle Royster learned about credit the hard way. In college, she signed up for a credit card to get a free T-shirt. Today she is the founder, CEO and CFO of Kimberly Services LLC and chairwoman of the Baltimore City Chamber of Commerce. She advises employers on financial and benefits strategies that protect their people.
When did you first start seeing the link between financial stress and people’s mental and physical health?
I think I’ve seen it almost all my life. I didn’t grow up with a silver spoon, as they say, and finances were always at the forefront of things.
I didn’t put it together until probably in my 20s. In my 20s, went to college, they offered me a credit card for a T-shirt, and I took it. Later on, had to look at myself and be like, okay, that probably wasn’t a good idea, but we can pay off that $500. Did that, rebuilt my credit, and learned what credit meant and the value of it. Once I’d learned that, I realized how many other people didn’t understand it.
Tell us about the survey. What does it tell us about how money worries show up as anxiety, sleep loss or burnout?
Some people just have financial stress. There’s nothing you can do about it. I can’t afford my bills. And then you have others that make decisions and don’t put the plan in place. Either way, they both come with this financial strain.
A lot of times we just want something. And that want turns into, oops, I probably shouldn’t have bought that, or oops, I probably should have put that in my savings. Or I need a new fridge, I need a new stove. So having that six months of emergency savings can help put you in a better place.
I always say every dollar you spend is every dollar you lose, so you want to plan out where your money is going. The first thing I see are subscriptions. People are subscribed to things that they do not use, and that is usually the first savings I find for most people, individual and business.
Can you tell us what risk businesses take when we underinvest in benefits for our employees?
I think a lot of times we’re not thinking about the future. Most business owners are like, look, I’m just trying to make it today. So it is all in planning.
Could you be paying somebody else to do it so you can make more money? The Baltimore Urban League has a restaurant accelerator program, and I did a presentation for their restaurants last night, saying, pick five things that you know you can’t stand doing, but you know it’s important, and delegate those five things. You can record yourself talking it through, and it will write it out for you, and now you have standard operating procedures for someone else to do it.
That’s an opportunity for you to make more money, or for you to take care of yourself. What I found was walking away from the business helped me make better decisions in the business.
Now you have this new person, I want to hire them. But it’s competition, so how do I compete? We do need to provide benefits for our employees. How do we get there? It’s called a plan. Today I can’t do it, but six to 12 months, I know we will get there. Once you open up the door, it just opens up more opportunity.
Can you tell us one common misconception we still have about financial stress?
I think a lot of times, it’s just the anxiety around money. A lot of us weren’t raised to manage money. I even had someone tell me, I just have anxiety to even open up my bank account. I’m like, okay, but how do you know you have enough money? And she’s like, I just hope it go through. And I’m like, no, we can’t live like that.
It is something called money trauma. It is real. Therapy is one of the first steps I always offer.
There’s also learning how to budget and learning how to plan. I tell everybody, do a paper day. Once a week, sit down and calculate everything I spent. It will help you make better decisions.
Does doing okay financially, but not spending on little things you can easily afford count as money trauma?
It could be. It’s almost like hoarding. I need a bunch of money, and I don’t want to spend anything, I don’t ever want to be broke again.
And it could be that she just doesn’t love it, and it’s not important to her, and that’s okay. But it might be that it is a trauma, be it she was broke, or she was homeless. Now she’s in a space of, I never want to feel that way again, so I’m never gonna buy me something nice. Even though I have a whole bunch of money sitting in the bank, mentally, I’m not comfortable with making that spend.
Can you tell us how you can help us handle our finances?
I’m revamping my website, but I do offer free budget templates. I also am creating a return on investment calculator, because we don’t always know what our return on investing is going to look like. I give tips all the time on ways to make better decisions.
Where can we find you?
My website is kimberlyservicesllc.com. You can also email me. It’s kroyster@kimberlyservicesllc.com.